A Certified Divorce Financial Analyst (CDFA®) is a financial professional credentialed by the Institute for Divorce Financial Analysts (IDFA) to analyze the financial side of divorce, working alongside your attorney. They value assets, model settlement scenarios, and analyze the tax impact of different outcomes, so you can make decisions with the full financial picture in view.
Most people entering a divorce know they need an attorney. What is far less understood is what happens to the financial picture: who models it, who stress-tests it, and who makes sure the settlement agreed to today does not carry a cost that only becomes visible years from now. That is the role of a certified divorce financial analyst (CDFA).
This post explains exactly what a CDFA does, how the CDFA® designation is earned, when it makes sense to engage one, and what to look for when choosing the right professional for your situation. If you're also weighing whether your case needs a forensic accountant, business valuator, or QDRO specialist alongside a CDFA, our guide comparing all three roles breaks down how to tell which one (or combination) you actually need.
Key Takeaways
- A Certified Divorce Financial Analyst (CDFA) is a credentialed financial professional who specializes in the financial side of divorce, not the legal side.
- This designation is issued by the Institute for Divorce Financial Analysts (IDFA), which has trained and certified divorce financial professionals since 1993.
- Modeling settlement scenarios, analyzing tax consequences, and clarifying the real long-term value of what you're agreeing to are the core of what a CDFA does, before you sign anything.
- Working alongside your attorney, not instead of one, is central to how a CDFA fits into your divorce team.
- Divorces involving retirement accounts, business interests, real estate, stock options, or total marital assets above $500,000 are where a CDFA adds the clearest value.
What Is a Certified Divorce Financial Analyst (CDFA)?

A certified divorce financial analyst (CDFA) is a financial professional credentialed by the Institute for Divorce Financial Analysts (IDFA) who specializes in the financial aspects of divorce. CDFAs model settlement scenarios, analyze tax implications, and assess the long-term financial impact of different asset division approaches. They work alongside attorneys and mediators as part of the client's divorce team, contributing financial analysis that informs negotiations and supports more effective outcomes.
The CDFA® designation exists because divorce is not a standard financial planning event. It involves a specific and overlapping set of considerations: asset and debt division, retirement account treatment, spousal support calculations, tax exposure on property transfers, and long-term cash flow projections. General financial planning training does not fully address these areas. The credential signals that the holder has studied and been tested specifically on them.
Most CDFAs come from backgrounds in financial planning, accounting, or wealth management. Before earning the designation, candidates must complete structured coursework and pass a comprehensive examination. The IDFA has been credentialing professionals in this discipline since 1993, making it the established standard in the field.
To see how this breaks down in a real settlement scenario, watch Jay walk through it below.
Video summary: A CDFA's core job during divorce is to model what a settlement actually costs and delivers over time, not just what it looks like on the day it's signed. That means comparing retirement accounts by after-tax value, not face value, and stress-testing whether keeping the marital home makes financial sense once carrying costs and capital gains are factored in. These are the same two gaps outlined above: retirement account division and the marital home.
What Does a Certified Divorce Financial Analyst Do?
The scope of a CDFA's work varies by case complexity, but the core tasks include:
Building a complete inventory of assets and liabilities: real estate, retirement accounts, investment accounts, business interests, deferred compensation, stock options, and outstanding debts
Running side-by-side settlement scenario comparisons that show what each option is worth after tax and over time, not just at face value today
Analyzing spousal maintenance or spousal support relative to long-term income and cash flow sustainability
Quantifying tax exposure on asset transfers, property sales, and retirement account distributions so that "equal" splits are evaluated on real value, not nominal value
Reviewing and preparing financial affidavits, statements, and supporting documentation
Supporting mediation and collaborative divorce by providing objective financial analysis that both parties can work from
Analyzing retirement accounts that require a Qualified Domestic Relations Order (QDRO) to divide correctly, a step that is easily overlooked and costly to correct after a decree is finalized
Providing post-divorce financial projections so clients understand what their financial position looks like on the other side of the process
A note from our practice: In our work with clients, two areas consistently produce the largest gap between what a settlement appears to offer and what it actually delivers. The first is retirement account division, where differences in account type (pre-tax versus Roth versus pension) create meaningfully different after-tax values even when balances look equal on paper. The second is the marital home, where the combination of capital gains exposure, ongoing carrying costs, and limited liquidity often makes retention far less financially advantageous than the appraised value suggests. Identifying these gaps before a settlement is signed is precisely where CDFA analysis has the most direct impact.
How Is a CDFA Different from a Divorce Attorney?
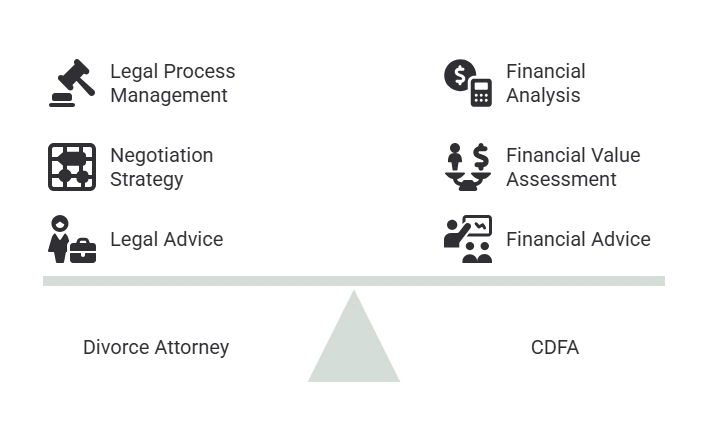
A CDFA and a divorce attorney serve distinct roles, and the two work best when they are working together. Your attorney manages the legal process: the filings, the court appearances, the negotiation strategy, and the language of the decree. Our team handles the financial analysis that runs alongside that process: what the numbers in the decree actually mean for your life going forward, and whether what sounds like a fair deal holds up when you run it out five or ten years.
Here is a practical example of how the two roles complement each other. Your attorney can negotiate for a larger share of a retirement account. Our team can determine whether that account is actually the more valuable asset once you factor in how each one is taxed on withdrawal. Both conversations need to happen, and they are most effective when they happen in coordination.
At Divorce Logic, we work alongside your attorney as part of your divorce team. We support your attorney and mediator with financial analysis that informs settlement negotiations and strengthens your position at every stage of the process, whether that is mediation, a collaborative divorce, or litigation. We do not provide legal advice and we are not a substitute for qualified legal counsel. Our role is to make sure the financial picture behind your case is accurate, complete, and clearly communicated so your attorney has something solid to work with.
What Is the CDFA Designation and How Is It Earned?
The CDFA® designation is issued by the Institute for Divorce Financial Analysts (IDFA), the premier national organization dedicated to the certification and education of financial professionals who specialize in divorce.
Earning the credential is not a short process. Candidates need at least three years of relevant professional experience in financial services, accounting, or a related field before they can even begin. From there, they complete structured coursework that covers divorce law and procedure, asset and property division, pension and retirement plans, the tax implications of divorce, spousal support and child support analysis, debt and credit, and financial planning fundamentals. Then they sit for a comprehensive exam across all of it.
Maintaining the designation requires 24 hours of continuing education and 2 hours of ethics training every two years. That ongoing requirement matters because tax law changes, financial regulations shift, and the financial issues that come up in divorce cases evolve alongside them.
The CDFA credential on its own is a meaningful specialization. Additional credentials go deeper into areas that frequently come up in complex cases. MAFF and CVA indicate training in forensic accounting and business valuation. CFP® signals long-term financial planning expertise. Our team holds CDFA®, MAFF/CVA, CFP®, CQS, ChFC, and WMCP designations, which reflects the range of financial disciplines that high-asset divorce cases actually require.
When Do You Need a CDFA in Your Divorce?
The honest answer is: when the financial picture is complicated enough that getting it wrong would cost you more than getting it right would have. That typically means cases involving multiple asset types, retirement accounts, a business interest, significant real estate, or a marital estate above $500,000. In those situations, the decisions made during divorce play out for decades. The gap between a well-analyzed settlement and a poorly analyzed one is rarely small.
A 2025 Allianz Life study found that two in five divorced Americans, 40%, say their divorce derailed their financial retirement strategy, and separate research from Western & Southern Financial Group found that roughly 6 in 10 people who divorce after 50 report losing at least a quarter of their retirement savings.
Cases where a CDFA adds the clearest value tend to involve one or more of the following:
Defined benefit pension plans or multiple retirement accounts (401(k), 403(b), IRA, deferred compensation, governmental plans)
One spouse who owns or co-owns a business, where valuation methodology and the treatment of business income have a direct effect on both asset division and support calculations
Real estate beyond the marital home, including investment properties, vacation homes, or commercial interests
Stock options, restricted stock units (RSUs), or equity compensation that vests over time and must be valued and divided carefully
Significant income disparity between spouses that affects spousal support, an area a divorce financial planner models as part of the broader settlement picture.
One spouse who has been out of the workforce or significantly underemployed during the marriage, raising questions about income capacity and long-term financial sustainability
Suspected financial misconduct, undisclosed income, or hidden assets, at which point forensic financial investigation becomes part of the engagement
Cases proceeding through mediation or collaborative divorce, where objective financial analysis supports both parties in reaching an informed resolution
High-conflict litigation where financial documentation needs to be thorough, defensible, and clearly presented
One thing we consistently tell clients: engage earlier than you think you need to. When financial analysis starts before positions have hardened and before the other side has framed the key documents, there is far more room to identify issues and model alternatives. Many of the clients who come to us mid-process say the same thing afterward. Not that earlier engagement would have changed the law, but that it would have changed what they knew before they agreed to anything. If any of this sounds like your situation, the earlier you bring in a CDFA, the more room there is to plan for it.
Schedule a Confidential Consultation
Free, secure, and no obligation.
How Much Does a Certified Divorce Financial Analyst Cost?

What is worth considering is not the cost of the engagement in isolation, but what an uninformed or under-analyzed settlement costs over time. A retirement account valued without accounting for its tax treatment, a business interest accepted at stated book value rather than fair market value, or a marital home retained without modeling the carrying costs and capital gains exposure: each represents a financial decision with a long tail. The difference between an accurate analysis and an incomplete one is often measurable in five or six figures over a ten-year horizon. The IRS provides guidance on the tax treatment of property settlements and divorce-related transfers that illustrates how quickly those numbers compound.
For most cases with meaningful asset complexity, the cost of CDFA analysis represents a fraction of that long-term difference. To understand what engagement would look like for your specific situation, a confidential consultation is the most useful first step.
How Do You Find The Right Certified Divorce Financial Analyst?

The right CDFA is one whose experience matches the complexity of your case. Before engaging anyone, it is worth asking:
Do you hold the CDFA® designation, and can I verify it through IDFA?
How many divorce cases have you worked on, and in what states?
Have you handled cases like mine, involving business ownership, multiple retirement accounts, or real estate holdings?
Do you handle QDROs in-house or refer them out?
How do you coordinate with my attorney or mediator?
A qualified CDFA will be straightforward about their credentials, their process, and what falls outside their scope. If something feels unclear or evasive in that initial conversation, pay attention to it.
Watch out for practitioners who cannot verify their CDFA® credential, have limited experience with your type of case, resist working alongside your attorney, offer vague pricing with no written scope of services, or make promises about settlement outcomes. None of those are signs of a professional you want navigating a process this consequential.
Divorce Logic serves clients in New Jersey, New York, and Massachusetts, and works with clients nationwide through secure virtual consultations. Our team holds the CDFA® designation along with credentials in forensic accounting, business valuation, and financial planning. Every divorce financial service, including QDRO drafting and submission, financial forensics, business valuation, and lifestyle analysis, is handled in-house, so your financial picture stays coordinated under one team.
Work With a Divorce Logic Certified Divorce Financial Analyst
Divorce Logic was built to meet every one of these standards. Our team holds the CDFA® designation along with credentials in financial forensics, business valuation, financial planning, and QDRO drafting. Financial forensics, business valuation, lifestyle analysis, and retirement division are all handled in-house, so your financial picture stays coordinated under one team.
That coordination matters most with retirement accounts. Your settlement says how a 401(k) or pension should be split, but the plan only acts on the QDRO. Our QDRO drafting services are led by a Certified QDRO Specialist (CQS), so the order that divides each plan matches the analysis behind your settlement.
We work directly alongside your attorney, provide clear written scopes of service, and never make promises about outcomes. What we can offer is the financial clarity to make decisions you can stand behind.
Divorce is a financial event. Treat it like one from day one. A certified divorce financial analyst helps you see the full picture before you agree to something you can't undo.
If you're going through a divorce or considering one, schedule a consultation with a team that handles this work every day and knows what's at stake.
Schedule a Confidential Consultation
Free, secure, and no obligation
Frequently Asked Questions About CDFAs
What is a CDFA?
In divorce and financial planning, CDFA® stands for Certified Divorce Financial Analyst, a credential issued by the Institute for Divorce Financial Analysts (IDFA). The same acronym is used by unrelated organizations, such as the California Department of Food and Agriculture. Financial advisors, CPAs, and planners earn the CDFA® on top of their base profession to show divorce-specific training in settlement analysis.
What is the difference between a CDFA and a divorce attorney?
A CDFA and a divorce attorney serve distinct, complementary roles. Your attorney manages the legal process: filings, court appearances, and negotiation strategy. A CDFA handles the financial analysis running alongside that process, specifically what the numbers in your settlement actually mean for your life going forward. The two work most effectively in coordination, with the CDFA contributing financial analysis that gives your attorney something accurate and complete to work with.
How much does a CDFA cost?
CDFA fees vary mainly based on what's bundled into the engagement, not a flat base rate. A straightforward settlement-analysis engagement costs less than one that also includes forensic review, business valuation, or preparation for expert testimony in court. Ask upfront whether those services are included or billed separately, since that is usually where cost estimates diverge most from what clients expect to pay.
Is a CDFA the same as a divorce financial planner?
Not exactly. 'Divorce financial planner' and 'CDFA' aren't interchangeable; one is a credential, the other is a general title any practitioner can use. Our full breakdown of divorce financial advisor, planner, and CDFA terminology covers the distinction in more depth if you're deciding between professionals.
Can a CDFA testify in court?
Yes. In contested divorce proceedings, a CDFA can serve as a financial expert and provide testimony on matters such as asset valuation, income analysis, and the financial impact of proposed settlement terms. Their financial analysis can also be submitted as documentation supporting a position during negotiation or formal legal proceedings.
Does a CDFA work instead of or alongside my attorney?
Alongside. A CDFA handles financial analysis, including modeling scenarios, quantifying tax exposure, and valuing assets, while your attorney handles legal strategy, negotiation, and representation. At Divorce Logic, we work as part of your divorce team, supporting your attorney and mediator with financial analysis that informs better decisions at every stage of the process.
When is the right time to bring in a CDFA?
Earlier is better. Many clients engage a CDFA after the settlement process is already underway, which limits the ability to run thorough scenario analysis or identify issues before positions have hardened. Engaging a CDFA at the beginning of formal proceedings, or even before filing, gives you and your legal team the most flexibility and the most complete financial picture to work from.
Do I need a CDFA if my divorce is amicable?
An amicable divorce still involves financial decisions with long-term consequences. A CDFA supports mediation and collaborative divorce as effectively as contested proceedings. In those contexts, the goal is to help both parties understand the financial picture clearly so any agreement reached reflects accurate values and realistic projections, not assumptions that one or both parties may later come to question.
How do I verify someone's CDFA® credential?
The Institute for Divorce Financial Analysts (IDFA) maintains a searchable directory at institutedfa.com/find-a-cdfa where anyone can confirm whether a professional's CDFA® certification is current.
Ready to understand what a CDFA can do for your situation? Schedule a confidential consultation.

Jay Mota, MAFF, CVA, CDFA, CFP, CQS
Founder and Principal of Divorce Logic
Jay is a nationally recognized divorce financial professional and has worked in financial services since 1997. As a divorce financial forensic expert, Jay reviews and analyzes the financial circumstances of individuals who are considering, navigating, or finalizing a divorce. He provides insight, analysis, projections, and strategic guidance to clients and attorneys to support informed decision-making and potential settlement.
Jay serves clients in all 50 states, helping them navigate complex financial situations during divorce with confidence and clarity.